Totaled but Still Loaded: Your Access Rights to a Wrecked Car's Dashcam, Navigation, and Trip Records
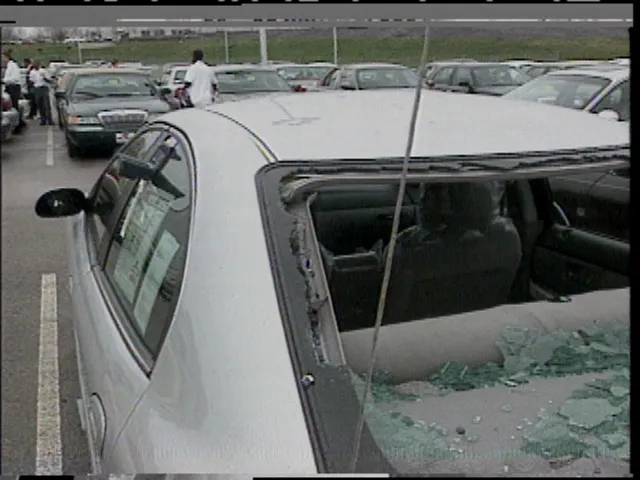
Photo: Uncredited for US National Weather Service, Public domain, via Wikimedia Commons
The adjuster's call comes quickly. The car is a total loss, the tow truck is scheduled, and the settlement paperwork is on its way. What almost nobody mentions in that conversation is that the vehicle sitting in the driveway is a filing cabinet on wheels, holding months of location history, hands-free call logs, paired phone contacts, and possibly a dashcam card with the only objective record of what happened.
Once a title transfers to an insurer, the vehicle is no longer yours, and access becomes a favor rather than a right. The window for retrieving data is short and it closes without announcement. The following is a practical and legal map of that window.
What a Modern Vehicle Actually Stores
A late-model car is a network of computers, and several of them retain user data long after the ignition is off.
The dashcam or dashcam app. Factory-installed recording systems and dealer-installed accessories store clips on internal memory or a removable card. Aftermarket units almost always use a microSD card that can simply be removed, which is the single easiest recovery action available.
The infotainment head unit. This is where paired phones leave their mark: contact lists, recent call logs, text message previews, and sometimes cached media. Saved navigation destinations, home and work addresses, and previous routes are typically stored here as well.
Telematics and connected services. Subscription services record trip history, mileage, fuel or charge data, diagnostic codes, and in some cases driving-behavior scores. These records live on the manufacturer's servers, not in the car, and they are governed by the service agreement rather than by the vehicle's location.
The event data recorder. The EDR, often called the black box, captures a few seconds of pre-collision parameters such as speed, braking, and seat belt status. Access is restricted by federal and state rules, and the data generally belongs to the vehicle owner or is retrievable through legal process. This is the one category where you should not improvise.
The First Forty-Eight Hours
Insurance settlements move on their own rhythm, and the vehicle can be relocated before a policyholder has thought about data at all. Three actions belong at the top of the list.
Say it out loud, in writing. Send the adjuster an email stating that you intend to retrieve personal electronic data from the vehicle before it is sold, moved, or crushed, and ask for the retrieval to be scheduled. A written record created early is far more persuasive than a request made after the car has left the lot.
Read the release before signing. Total-loss paperwork frequently includes language transferring the vehicle and its contents to the insurer. Some policies and state forms address personal property explicitly; others do not. Ask which clause covers removable electronics and data, and request an amendment if the answer is unclear.
Remove what is plainly yours. A dashcam memory card, a USB drive in the console, a phone mount, and a charging cable are personal property. Retrieve them at the scene or at the tow yard if you can do so safely and lawfully. Do not disassemble trim panels or attempt to pull the head unit yourself.
Asking the Insurer or Salvage Yard for Access
Insurers are accustomed to requests for personal property left in a totaled vehicle, and many have a process for it, even if the front-line adjuster has to look it up. Frame the request around specific items rather than general access: the dashcam card, the infotainment system's saved data, and the paired phone records.
If the insurer declines, ask for the reason in writing. Policies vary, and state insurance regulations differ on how personal property in a towed vehicle must be handled. Salvage auctions and Copart-style yards generally do not permit customers to pull parts, but they often allow retrieval of personal belongings with documentation and an appointment. The insurer, as the current owner of record, is usually the party who must authorize it.
A workable request asks for thirty minutes with the vehicle, a technician or lot attendant present, and permission to unpair phones and manually delete personal data afterward. Offering to sign a waiver for damage during retrieval removes the most common objection.
Extracting the Data Without Leaving Your Life Behind
If access is granted, the goals are extraction and erasure, in that order.
Pull the dashcam card and copy its contents to two devices before viewing. For the head unit, use the manufacturer's own export or backup function where one exists; several brands support profile export to a USB drive. Where no export exists, photograph the saved destinations and call history screens, which is inelegant but preserves the information.
Do not connect your current phone to the vehicle's Bluetooth to browse its memory. Pairing creates a new record and may sync contacts in the wrong direction. Bring a blank phone if a pairing is unavoidable.
Once the extraction is complete, unpair every device, delete the stored phone profiles, and clear the saved destinations and home address. A salvage buyer, a mechanic, or the next owner should not inherit your contact list. If the insurer permits it, a factory reset of the infotainment system is the cleanest finish.
For telematics and connected-services data, contact the manufacturer's account team directly and request a copy of your trip and diagnostic history before closing the subscription. Those records are tied to your account rather than the hardware, so they remain available after the vehicle is gone, provided the request arrives before the account is cancelled.
Where the Law Leaves the Decision
The legal position is less protective than most drivers expect. Until the title transfers, the vehicle and its data are yours and access is generally straightforward. After transfer, the insurer owns the hardware, and your claim to data stored on it rests on the policy language, the salvage operator's goodwill, and the willingness of state regulators to enforce personal-property rules.
That asymmetry is why the request must be made early and in writing. A totaled car is a legal transaction first and a data-recovery problem second. Treat the email to the adjuster as the most important file you will save that week.